 Ecouter sur Spotify
 Ecouter sur Apple podcast
 Ecouter sur Deezer
 Ecouter sur Amazon music
 Ecouter sur Ausha
“That’s the real advantage of next-gen cores: you don’t have to modernize everything at once. These platforms are built for progressive renovation, which means you can take it step by step. That makes all the difference. For example, we’re currently working with NS&I, one of the UK’s largest government-backed institutions with around 14 million customers. They’re taking a progressive modernization approach: we’re phasing out their legacy systems piece by piece, starting with savings products and some payment functionalities. It’s a smart, lower-risk way to manage such a major transformation, and a great example of how next-gen cores enable real, practical change at scale.”
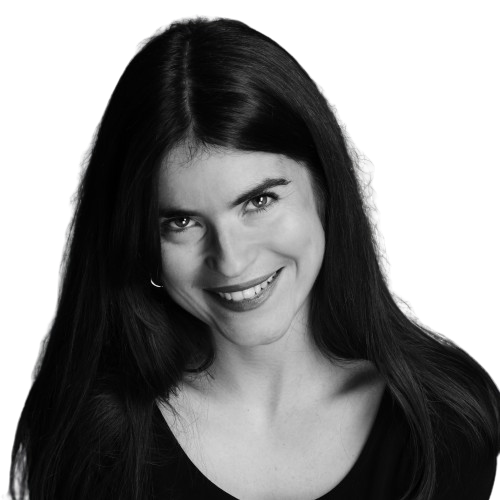
Valmina Prezani, Head of Product Management for Digital Core at SBS
In this episode, we explore how next-gen core banking platforms are transforming the industry, one customer journey at a time. Our guest, Valmina Prezani, Head of Product Management for Digital Core at Sopra Banking Software, walks us through what it really means to build a core system around customer needs, not just operational efficiency. From shifting expectations in both retail and corporate banking to the challenges of moving away from legacy systems, we unpack what’s holding banks back and how a modern core can be a true strategic enabler. Valmina also shares real-world examples, best practices, and advice for banks ready to modernize without disrupting what matters most: the customer experience. Let’s dive in.
Podcast transcript
Caroline Béguin: Welcome to Fintrends, the podcast by SBS where we explore what’s shaping the future of finance with insights straight from industry experts. Today’s topic is core banking. The sector has changed permanently, and with rising expectations and fast-moving tech, banks need to rethink their foundations. And that starts with a bold shift, reimagining core banking through a customer-first lens. And to explore this topic, I’m thrilled to welcome Valmina Prezani, head of product management for Digital Core at SBS. Hi, Valmina. Thanks for joining us.
Valmina Prezani: Hello, Caroline. Thank you for having me.
Caroline Béguin: So before we dive into all this, can you tell us a bit about yourself and your current role at SBS?
Valmina Prezani: I joined SBS, I think, three, four months ago now. As you said, I’m the head of product management for Digital Core. I’ve been working in this industry for twenty years now, more than I would like to remember, I think. We’re getting to that stage right now. I started my career working for a much smaller company, which was actually a systems integrator that was then acquired by another big core banking vendor, and that’s how I ended up here. And I’ve done quite a lot of things, but for the last decade, I’ve been focusing on product management. The role that I have in SBS today is to take our product management practices to a whole new level. I hope, at least this is my aspiration, driving a much more market-focused, solution-driven, let’s say, approach on how we do product management. And I think core banking and digital core is probably the best place to start from. So that’s me.
Caroline Béguin: How would you describe the shift in customer expectations in banking over the past few years? And I’m talking about retail and corporate customers.
Valmina Prezani: So it’s been something that’s been happening for quite some time. I would say that this whole thing started probably ten or fifteen years ago, but I think the last few years have seen a massive acceleration of all the big shifts that you alluded to. So I think technology has had a massive role in this shift, especially what has happened in the last decade has created a whole new type of customer. And the newer generations that are coming, they’re digital natives, they’re born with a phone in their hands, right? So their experience and their expectations and their needs are very different to what we have been accustomed to for decades. So this creates a challenge, let’s say, for the traditional banks because they never had to think about those customer needs and expectations up until now because banking was banking. Everyone needed to have a bank account. We still do. There were a set of institutions offering these products. There was a set of products that were being offered, and you just had to get one. There was no real choice involved. But now there has been disintermediation in the financial services industry for the last ten, fifteen years, where regulations have opened up and entrants are coming in that are not necessarily banks. They could be big tech, they’re fintechs, and they’re chipping away parts of the value chain because they’re offering much better customer experiences, but also product offerings. Like, their propositions are actually more compelling and more appealing to the next generations, let’s say the ones that are coming, who are definitely used to a very different experience. Because if you see what has happened in all other industries, they’re expecting the same level of service. They’re expecting the same level of choice that they have in terms of products, and there’s no real loyalty involved anymore. Like, whoever is offering you the better perk or the better price or the better reward or all of the above, the better bundle of all of these things will get your customer in the end. This is a very new thing for traditional banks, and I think a lot of them have been struggling because it’s a very different operating model than what they have been used to, for decades and decades.
Caroline Béguin: I’m interested in your perspective on what it really means to adopt a customer-first lens in banking.
Valmina Prezani: I think it’s not just a banking question. We all need to have a customer-first lens. Every industry, every organization, we have to know our customers, and we have to care about what they need and what they would be willing to pay for. Otherwise, we would all be out of business. But what does it mean? For me, a product is a promise that we make to a customer, and that goes for you and me, right? So when we go and buy something, we’re buying a promise that someone is making to us that they’re either gonna solve a pain point or a problem that I may have, or they will satisfy a need that I may have or I may not even know that I have, but they can create it for me. So having that knowledge and that insight to be able to understand your customers, understand their needs, understand their expectations, and create the right product propositions to address those. Ultimately, though, it’s to make the customers’ lives better. And for me, this part is extremely important. I think we all work for a purpose, so for me, making someone’s life better is a personal driver of mine, so I want to do things that would eventually help people live better lives. I think it’s quite important to keep that frame of mind because ultimately that’s how you create loyalty as well.
Caroline Béguin: What you describe is the ideal purpose.
Valmina Prezani: Yes.
Caroline Béguin: So how far is banking today from what consumers need?
Valmina Prezani: We have to segregate now between what we call traditional banks and what we call neobanks. I will focus my answer on the traditional banks because also they are, let’s say, the biggest part of our customer base. But traditional banks, unfortunately, they’re not close to what customers need, at least this is my personal opinion and belief. Which of course you can substantiate it with what’s happening out there in the market and what you see coming out of traditional banks and what’s coming out of neobanks or fintechs such as, you know, Revolut, right? Traditional banks never had to worry about these things for decades. They were a very protected industry. Everyone had a customer base because everyone had to have a banking relationship of some sort. And also, in the older days, and when I say older days, let’s say maybe fifty years ago or sixty years ago, people would open a bank account with the bank down the road, and then they would probably stay with it for the rest of their lives, right? And their families would bank, and their children would bank, and their grandchildren would bank with them. So it was a very different environment, and they never had to worry. Like these were the products. You either take it or leave it, and that’s about it. This doesn’t happen anymore, but I think because this was ingrained in the way they were working and the way the industry was, they didn’t have a compelling reason to change and of course, the regulation protected all of that. So now, with everything that has happened in the last ten, fifteen years with the new frameworks, new regulations coming in, opening up, like dropping the barriers to entry that banking had and allowing fintechs, big tech, and anyone actually to enter this space and offer something to these customers and to the newer customers, it has created a situation where they have been struggling quite a bit. The nature of banks is that they are resilient to change. They’re by nature risk-averse organizations, and that’s okay. They have to be. But because of that, I think they did not grasp the importance and the need to, to basically change the way they operate and the way they think about their customers and the way they do their products management and the way they design their offers and product propositions and everything. And I think there was a disbelief, let’s say, that this is gonna take off or that they’re gonna have an issue. So it took several years for them to start realizing that they have to do something about it. I think that’s gone now, especially in the last, let’s say, maybe five to seven years. It has been quite evident that they have no other choice. But the change that we’re asking them to do is so big because we’re asking basically an organization that, as we said, is resilient to change, risk-averse. It’s all about safety, security, which by the way is also one of their biggest advantages of traditional banks. But it’s still very different to what the newer generations that are coming need and expect because they expect innovation and cool technology and an impeccable customer experience in everything that they do. So we’re asking banks to work like tech companies and change their DNA, and we’re asking them to do it really, really fast now. Well, they have to because that’s where customer demand is, and it’s actually quite hard for them.
Caroline Béguin: So to change, banks have to modernize their core system. When we talk about a modern core banking platform, what is a modern core? What are we talking about?
Valmina Prezani: So it’s basically a core banking system that enables the bank to achieve everything that we just talked about in a way, but it means that it’s using the latest technology. It’s using best-of-breed technology. It’s open. It’s composable, so it’s broken down into little pieces that you can put together in the way that you want. It’s API first. It’s SaaS native or SaaS first, whatever you wanna call it. But basically, it enables the bank to leverage all the latest technologies. It’s data first, yeah, artificial intelligence models, like all of these things have to be there to enable the bank to, to sort of achieve what they want to achieve and become definitely more agile and more relevant with what’s happening today in the market. It’s about distributed architecture. It’s about scaling and performance. It’s about integration and ecosystem creation, so understanding that you can’t do everything anymore, and you need to build that ecosystem. So it’s enabling all of that, our infrastructure and architecture, so you can do all of the things, and you can build those propositions, and you can have this compelling customer experience. And it’s quite crucial to have something like that in the back end because the front end is there and it, it can do a lot of things, so the engagement layer and distribution layers are there to, and can enable a lot of these things, but if the back end is not able to support all of these new technologies and leverage them, then there is a limitation to what your engagement layer can do. So that’s why I’m saying it’s an overall solution, but it’s a foundation to basically disrupt and innovate and take a leap forward.
Caroline Béguin: And what role do the regulators play in all this?
Valmina Prezani: Regulators are probably the most important dimension for banks, and not just banks. And the role is multifold. It’s not just one. They’re an enabler, but they can also be a hindrance, so at the same time, right? Up until recently, regulators and regulation and compliance in general was mostly a hindrance to banks. And to the rest of the world because not many people could break into the financial services sector because of regulation and because of compliance and because of licenses and all of these things. I think there has been a mass-massive shift also in that space in the last few years because I think regulators have perceived this, and they have shifted the perspective to become enablers rather than hindrance. And this can be seen with all the new things that are coming out from open banking, PSD, two, three, you know, everything, customer-related regulations. And you can see that some are there to protect, which is absolutely fine, and some are there to enable, and that’s how new players and new entrants have managed to come into this whole space and bring more competition. So they have a massive role. Regulation is probably the one of the main business drivers that banks change. It’s one of the compelling events that banks would usually have to do anything internally in terms of how they work and how they operate.
Caroline Béguin: But if they don’t, customers are gonna move to neobanks or…
Valmina Prezani: Well, if they don’t, first of all, the regulator is gonna fine them most probably. So it’s not really a choice. Well, yes, customers like you and me would probably go and get products or get banking relationships with banks that offer a much better experience. To say that, actually, I think we need to rephrase a bit this, let’s say, the topic and the question because even new banks or neobanks or fintechs, they have to comply with regulation. So compliance is a massive piece, and it has been a very difficult piece for the new entrants to grasp because regulation is not easy. Yeah. That’s why not everyone is doing it. So banks have had, and do have still today, a massive advantage compared to all of these new entrants that they could leverage to their benefit because they have been doing this for decades, and they have specialist teams and people and resources looking at these things and knowing how to be compliant and follow the regulations while offering products and good customer experience and everything. New entrants don’t necessarily have that knowledge, and it’s not easy to acquire and build that knowledge. So what I’m trying to say is that regulation is a very big part of banking, as we all know, and yes, it can be a hindrance, but it can also be an enabler. And for me, for traditional banks today, it could be a competitive advantage that they can use to their benefit compared to the other entrants and to the fintechs that are trying to build up new banks, new financial products, services, whatever it is.
Caroline Béguin: Now I’d like to know a reason for banks other than compliance to modernize their core banking. And I wanna know what difference modern core banking has in improving customer experience.
Valmina Prezani: As I said, any core banking system is the heart of the bank. You cannot live without a heart. So it’s extremely foundational and hence extremely important for everything else. If you have a weak heart, you’re gonna suffer, right? It’s the same with a bank, like if we can draw this analogy. Keeping up to date and modernizing, it’s like keeping fit in a way, right? But it’s not an easy task because changing your core banking system is like having open heart surgery on a patient who’s still awake. So it’s a very tricky situation, and this is why we have an industry around it, and this is why there has been a lot of people, vendors, integrators, consultancies, making a lot of money out of this for the last, I don’t know, 20, 30, 40 years or more. It is extremely important to modernize your core throughout, let’s say, your life as an organization, and it’s not just about regulation compliance. Of course not. Regulation is just one main driver for banks to change, right? But it’s basically to be able to offer a better customer experience, to leverage your, you know, all of these engagement tools that you have today to be able to offer a compelling experience and product proposition to your customers. And not just one product, product in a loose, let’s say, a concept. It can be a bundle, it could be a combination of services. It could be a combination of products that are not even just financial products, yeah? So let’s keep that as broad as possible. But if you want to leverage all of these capabilities and make your customers’ lives better, you need to be able to have the foundations and the infrastructure that will support that. And if you don’t have a modern core, you can’t really do that. It’s limiting. Like you can get to up to a point, but then you can’t really do much else. And for me I always used to say that, I’ve been saying that for the last 10 years. If you just change your front end without doing anything on the back, it’s like putting lipstick on a pig. Like you’re trying to beautify something from the outside without trying to change the inside. And we all know that real change comes from the inside, not the outside.
Caroline Béguin: What would you say to banks who would tell you that it’s just a cost center?
Valmina Prezani: Yes, it is. I would not say that it’s not. But that doesn’t mean that it’s not important. And sometimes it’s not just about profit maximization, it’s also about loss minimization. So yes, it is a cost center, but it’s an extremely important cost center that can help you increase your profits if it’s more cost efficient, on the one hand. It can also help you minimize your losses. When I say minimize losses, it could be on losing customers, so customer churn. So with a better core, hence a better customer experience, if you take your engagement and distribution layers combined with a modern core, you can actually retain more customers. You can create a more loyal customer base. You can make your customers more profitable, especially if we inject, you know, data and AI in there, right? So all of this together can minimize your losses and also increase your revenues and hence profits. And a modern core will allow you to run at a much lower cost than your legacy systems. So if you put all of these three things together, yes, it is a cost center, but it can actually provide quite a lot of benefit.
Caroline Béguin: And transitioning from a legacy core to a modern one is a big leap. So what are some common challenges banks face during this kind of transformation?
Valmina Prezani: I think that’s the million-dollar question, Caroline. There are several. It depends on the bank, of course, because every organization is unique in some shape or form. So the challenges can range from senior leadership buy-in, so not enough of it, to technology constraints, to users, bank users, you know, not willing to adopt change. It could be, it could be several. But I think the most important thing that most banks struggle with is the risk that these projects entail. Core banking transformations are quite lengthy in duration. It doesn’t matter how small or big you are, unless you’re a neobank, so unless you’re an absolutely new bank putting something from scratch, it will take a few years for you to be able to transform your core, and there is a lot of risk involved. As I said, it’s like having open heart surgery with an awake customer, so you need to be able to keep operating and keep servicing while you’re doing all of this change in the back end. It’s quite tricky, and risk is the main driver and the main challenge that banks are thinking about when they want to enter these projects. On top of that, because they’re so lengthy, a lot of senior leaders struggle with making the right choices and the bold choices that they need to make because up until now, like when you didn’t have next gen cores around, such projects would last at least five years, right? It was definitely more than three. That is basically more than the average duration of a C-level executive in a bank. And most of the time, people who are making those decisions, it’s like putting your own head on the line. So if they’re successful, it’s great and it’s a legacy. But if it’s not, and in a lot of cases they weren’t, it’s basically your head. So with that in mind, being a cost center as well, with the way that macroeconomic conditions have been, I think everyone has been focusing on short-term profits, a short-term view of the world, let’s say. These types of decisions and these types of projects have always been quite hard. But now that’s the beauty with the next gen cores because you don’t have to do it in one go. That’s the whole idea of a progressive renovation or progressive modernization approach, where these platforms, such as Digital Core, enables you to do this one step at a time. That’s where the next gen cores actually make a huge difference. And as an example, we are now working with a very big UK institution, NS&I, who are following this approach. We are literally going through a progressive modernization approach where we’re taking their old legacy core and we’re hollowing out one piece at a time. So we’re doing their savings products, and we’re doing some of their payments, and there is a progressive approach to the project with certain things going live first, and so on and so forth. It’s actually very interesting and a good example because NS&I is one of the biggest institutions in the UK. It’s a government institution. It has circa forty million customers. There are so many people relying on it, so for them to be able to enter into such a transformation, they need to be able to de-risk it, and this is basically a very good way to do it.
Caroline Béguin: So from your experience, can you provide solutions and best practices for overcoming these challenges?
Valmina Prezani: I think it’s a very particular question because, again, it depends on the bank we’re talking to, and I think knowing your customer is extremely important. So I can give you a few generic ones, let’s say. But I’m a massive proponent of you have to know your customer. So you need to know who you’re talking to. You need to listen to them. You need to know what their specific pain points are because it could require a slightly different approach or answer or prioritization or whatever it is. But buy-in from senior management and strong support for these types of programs are absolutely necessary. It’s critical. If you don’t have that, the project is bound to fail. Even if it’s a progressive modernization thing or it’s a full core banking transformation, it doesn’t matter. If you don’t have the right buy-in, it won’t work. And you need to be able to get that buy-in to trickle down to the whole organization. From my experience, this has been one of the key challenges that I have seen with all of these projects in the last twenty years. Even when there was buy-in from senior leaders, if there was no proper communication downstream, the project would also fail. Because there was a big disconnect between what was happening upstairs and what was happening on the day-to-day within the bank. You also need to have a very clear vision and strategy of where you wanna go and where you wanna be. I’m talking from a bank’s perspective right now, and I think that’s where we, core banking vendors, can actually help because we can help with advising on the shaping of that vision and approach. But then also we can help the banks shape the journey to get there because it’s not gonna be an easy journey. We know that. But we can actually help them shape that journey in the right way for them to manage risk, to do this properly, to secure success, to start showing business value to their customers early on, while all of this is ongoing. So for me, our role is to also shift from a vendor to an advisor, and I think when we have managed to do that, in my career, in every single project we managed to do that, these projects were probably the most successful that we have had. Banks do need the help because a lot of the time, they don’t know how to do this transition. They don’t know from knowing their customers to knowing their new customer needs technology. They don’t know, and they need guidance and help in doing so, and we have the business experience and the technology experience to be able to advise them.
Caroline Béguin: What’s one piece of advice you would give to a bank that’s hesitating to start its core transformation?
Valmina Prezani: Don’t wait. You have to do it. It’s like, “It’s now or never,” type of thing. I think we’re reaching a tilting point. Even to this day, there has been, and there still is in my opinion, quite a lot of resistance within traditional banks to change. But I think we’re reaching a pivotal moment where people who don’t change, or banks rather that don’t change, won’t make it, and the ones that do will. And then we’ll see all these new entrants like the neobanks and the fintechs, and actually we’ve been seeing it already, right? So some of them are now banks themselves, and they started from, you know, a fintech operation, and they’re now multi-billion dollar operations listed and you name it. So we’re reaching a point where there is no debate anymore whether change is needed. Change is definitely needed, and you need to really take the leap and jump on it. But what I would advise is find the right partners to do it with. So don’t wait, but find the right mix of partners that would help you do it. And it’s not the same for every bank.
Caroline Béguin: To wrap up this podcast, I’m interested in what excites you most about the future of core banking.
Valmina Prezani: A lot of things excite me at the moment because of the latest developments with artificial intelligence. It scares me at the same time. I’m not gonna lie, and I’m a tech person, right? And I’m also scared. The thing with every new discovery or invention, which is as big as artificial intelligence, there’s always two ways that we can use this. There are ways that we can use it that can help humanity as a whole and make everyone’s life better, make our planet better. But obviously, it can be used in very destructive ways at the same time. So we have to be very careful. Not just me and you, I mean worldwide governments, policymakers, big corporations. We have to be very mindful of how we’re gonna use this technology to actually leverage it for the good of everyone. Possibility-wise, what’s happening right now and what will happen in the next five, 10 years, I think it’s going to be revolutionary across all levels. It can be. From jobs to quality of life, to medicine, to you name it, banking included in all of this, right? But I’m also very scared at the same time because history has shown that unfortunately human nature is slightly greedy. So to me personally, as Valmina, because as I said, I do have a purpose and I do wanna create things that make people’s lives better. We can democratize, let’s say, banking, but in a way that is enabling people and helping them to build a financial future that helps them reach their dreams and their goals. We can actually do all of that, whether it is financial education or whether it is the right products at the right time for the right person, whether it is like smart signals that pick up things and say, “Oh, something is happening on the life of that person. What’s going on? Let’s figure out how we can help them, how we can support them.” The possibilities are immense, and we can actually create something that would help every single one of us have a much better life. I hope we focus on that as a whole instead of the destructive aspects of what could potentially happen.
Caroline Béguin: I hope that too.
Valmina Prezani: Yeah exactly. Because of all of these new technologies, they can really, really make a huge difference to the whole world.
Caroline Béguin: Okay. That’s great to know. Thank you so much, Valmina, for being with us, for sharing your insights and for sharing your time.
Valmina Prezani: Thank you, Caroline. It was lovely to be here. Thank you so much. Looking forward to doing this again with you.